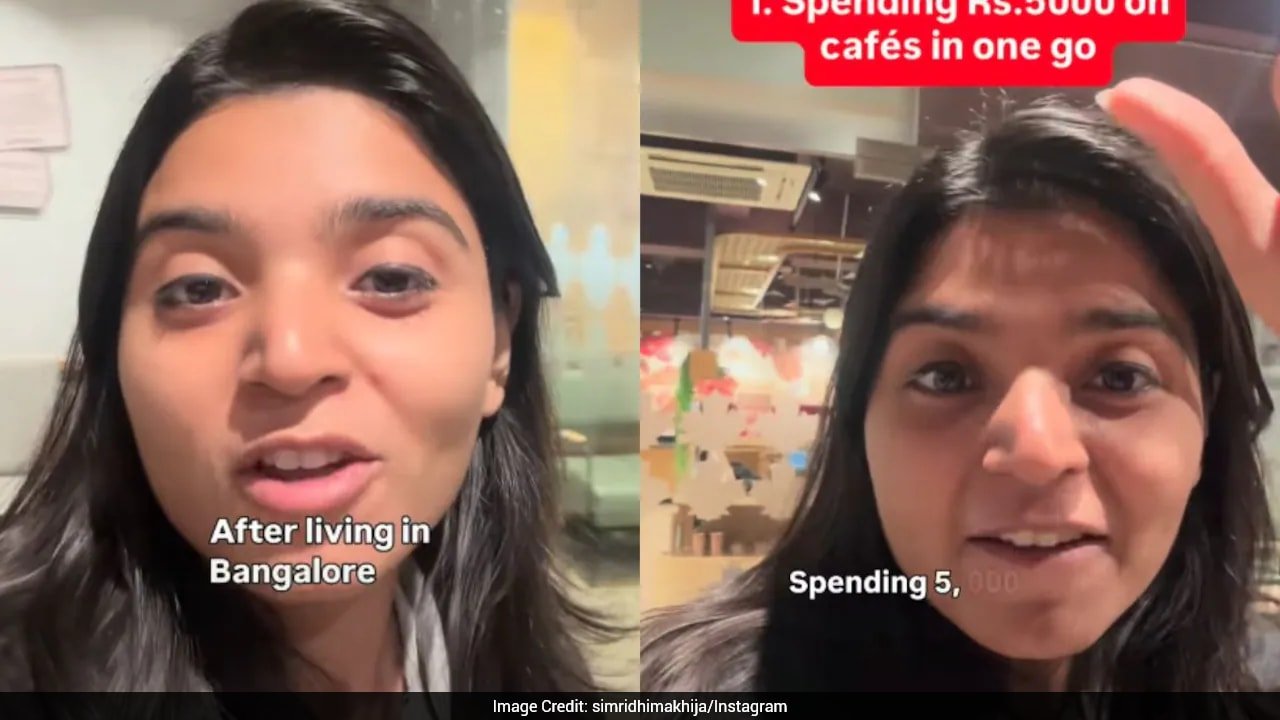
In recent years, India's bustling tech capital, Bengaluru, has frequently found itself at the epicenter of cultural debates, ranging from skyrocketing rental prices and grueling traffic congestion to the fast-paced lifestyles of its massive young workforce. Now, a fresh discourse has taken over social media platforms, sparking intense discussions about modern financial habits. At the heart of this viral debate is Simridhi Makhija, a newcomer to the Silicon Valley of India, who recently took to Instagram to question the spending patterns of the city's younger demographic, advocating strongly for a return to traditional financial prudence and aggressive saving.
The Viral Video That Sparked a Financial Debate
Simridhi Makhija, who relocated to Bengaluru just seven months ago, has quickly experienced the unique socio-economic ecosystem that defines India’s startup capital. In a video shared widely on Instagram, Makhija expressed her astonishment at how freely young professionals in the city spend their hard-earned money. From frequent fine dining and weekend getaways to high-end lifestyle purchases, she observed a distinct trend of immediate gratification over long-term security. Her core message was simple yet provocative: in an era of economic uncertainty, the younger generation needs to curb reckless spending and prioritize building a robust savings portfolio.
The video immediately struck a chord across the internet, dividing netizens into two distinct camps. On one side, many seasoned professionals and financial advisors echoed her concerns, pointing out the dangers of lifestyle inflation. On the other side, a vocal segment of Gen Z and younger millennials defended their lifestyle, arguing that high burnout rates in corporate jobs justify spending on experiences today, especially given the unpredictable economic future and soaring real estate prices that make traditional milestones like homeownership increasingly out of reach.
Understanding the Financial Dilemma of Urban Youth
To truly understand Simridhi Makhija’s perspective, one must examine the unique economic landscape of cities like Bengaluru, Mumbai, and Gurgaon. These urban centers attract lakhs of ambitious graduates every year, offering lucrative salaries that are simultaneously offset by high costs of living. For many, this is the first time they are experiencing financial independence. Coupled with the influence of social media culture—where curated lives dictate success—the pressure to maintain a certain standard of living has never been higher.
Financial experts often refer to this phenomenon as lifestyle inflation, where an increase in income results in a discretionary increase in spending rather than savings. While indulging in occasional treats is healthy, the lack of a financial safety net can lead to long-term vulnerability. Makhija’s commentary highlights a generational divide in how money is perceived: older generations view savings as the ultimate metric of security, while the younger cohort increasingly values experiential spending and mental well-being.
Key Factors Driving Modern Spending Habits
Several socio-economic drivers contribute to why contemporary youngsters spend differently compared to previous generations:
The Post-Pandemic Mindset: The global health crisis served as a stark reminder of life's unpredictability, leading many young adults to adopt a "You Only Live Once" (YOLO) philosophy, prioritizing travel and experiences over hoarding cash.
Instant Gratification Economy: The rise of quick-commerce, food delivery apps, and buy-now-pay-later (BNPL) services has made spending frictionless, lowering the psychological barrier to parting with money.
Peer Influence and Social Media: Digital platforms constantly showcase hyper-curated lifestyles, creating subtle yet powerful pressures to keep up appearances.
Analyzing the Spending vs. Saving Paradigm
To provide a clearer picture of how financial priorities are shifting among urban Indian youth, let us examine the core differences between traditional savings models and modern expenditure trends through the data breakdown below.
| Financial Metric | Traditional Approach (Older Generations) | Modern Approach (Bengaluru Youth) |
|---|---|---|
| Primary Focus | Long-term capital accumulation, real estate, gold | Experiential living, skill upgrades, lifestyle goods |
| Emergency Fund | Extensively prioritized (6 to 12 months of expenses) | Often neglected or kept minimal |
| Credit Usage | Highly conservative; aversion to debt | Widespread use of credit cards and BNPL for lifestyle |
| Investment Style | Fixed Deposits, Public Provident Fund (PPF) | Mutual funds, equities, crypto, high-risk assets |
Striking the Right Balance: The Path Forward
While Simridhi Makhija's warning about the dangers of excessive spending holds immense validity, financial planners also caution against extreme frugality that compromises one's quality of life. The ideal approach for young professionals living in high-cost tech hubs lies in achieving a sustainable equilibrium. Implementing structured budgeting frameworks, such as the popular 50-30-20 rule—where 50 percent of income goes to needs, 30 percent to wants, and 20 percent to savings—can help bridge the gap.
Furthermore, investing early through Systematic Investment Plans (SIPs) allows the youth to harness the power of compounding without entirely giving up their lifestyle choices. Financial literacy must go hand-in-hand with career growth, ensuring that the vibrancy of city life does not come at the cost of future financial independence.
Conclusion
The viral debate sparked by Simridhi Makhija’s observations in Bengaluru touches upon a universal struggle faced by modern youth: navigating the tension between enjoying the present and securing the future. As urban centers continue to evolve as melting pots of ambition and high-speed living, conversations around financial discipline will only grow more critical. Ultimately, whether one chooses to save aggressively or spend on experiences, conscious decision-making remains the cornerstone of true financial wellness.

