Source: The Hill
Introduction
A contentious debate is brewing in Washington regarding the future of federal healthcare consumer protections. Critics are sounding the alarm, suggesting that powerful entities within the insurance industry are orchestrating a strategic effort to undermine the No Surprises Act.
As Big Insurance faces scrutiny over these alleged maneuvers, lawmakers are being urged to intervene. There is growing pressure for both the House and the Senate to launch formal investigations into whether these industry players are successfully gutting the signature patient protection law designed to shield Americans from unexpected medical bills.
What Happened
The core of the current controversy centers on reports that influential insurance corporations are attempting to weaken the regulatory framework established by the No Surprises Act. This landmark legislation was initially crafted to prevent patients from receiving exorbitant out-of-network bills for emergency services and certain non-emergency care provided at in-network facilities.
Observers argue that the legislative intent of the act is being compromised by aggressive industry tactics. By lobbying for changes to the law's implementation, these corporations may be effectively eroding the protections that Congress worked to codify. The situation has prompted a call for legislative oversight to ensure that the original spirit of the patient-centric law remains intact.
Background
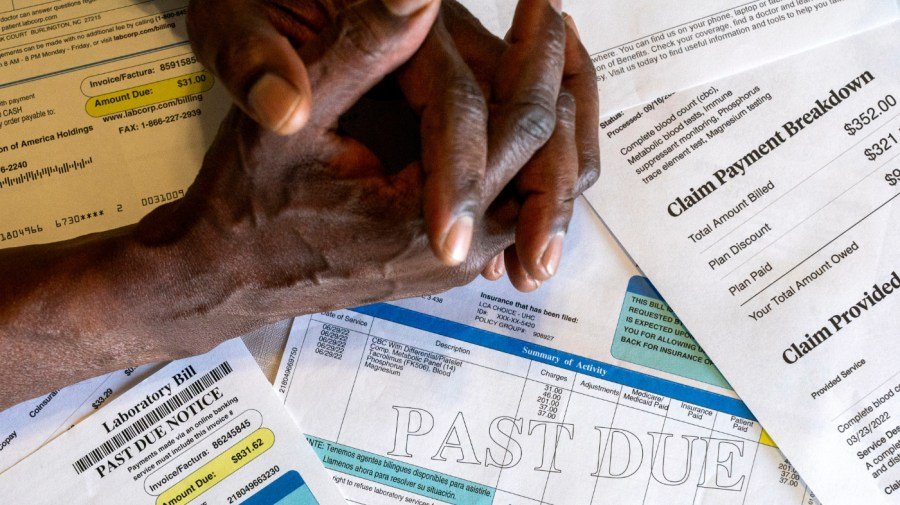
The No Surprises Act stands as a significant milestone in federal healthcare policy, specifically designed to address the financial distress caused by surprise medical billing. Prior to its enactment, patients frequently found themselves liable for substantial gaps in coverage when they unknowingly received treatment from providers outside their insurance plan's network.
The legislation was intended to serve as a definitive safeguard for consumers, ensuring that financial disputes between insurers and healthcare providers do not burden patients. It created a structured process for resolving payment discrepancies, aiming to stabilize the healthcare marketplace while prioritizing the financial security of the insured population.
Key Details
The following summary outlines the primary actors and the legislative focus currently defining this policy dispute.
| Category | Details |
|---|---|
| Primary Legislation | The No Surprises Act |
| Accused Industry | Big Insurance |
| Oversight Bodies | The U.S. House of Representatives and the U.S. Senate |
| Primary Objective | Protection of patients from surprise billing |
Impact
If the efforts to undermine the No Surprises Act prove successful, the implications for the American public could be severe. The primary consequence would be the potential re-emergence of surprise medical billing, which would disproportionately affect patients who have no control over which providers treat them during emergency situations.
Furthermore, the integrity of federal healthcare reform is at stake. If major insurance providers are permitted to bypass or weaken established consumer protections, it may set a precedent for future policy rollbacks. The erosion of these safeguards threatens to shift the financial responsibility for medical costs back onto the patients, effectively reversing the legislative gains achieved through the act.
What Happens Next
The path forward remains contingent upon the willingness of Congress to exercise its oversight authority. Advocates for the law are calling for a formal inquiry into the activities of the insurance industry to determine if their actions constitute a deliberate attempt to dismantle the patient-protection framework.
Should the House and Senate initiate a formal investigation, the findings could lead to renewed calls for stricter enforcement or legislative amendments aimed at closing loopholes that insurers may be exploiting. The legislative response will be a critical indicator of whether the federal government remains committed to upholding the protections established under the No Surprises Act against corporate influence.