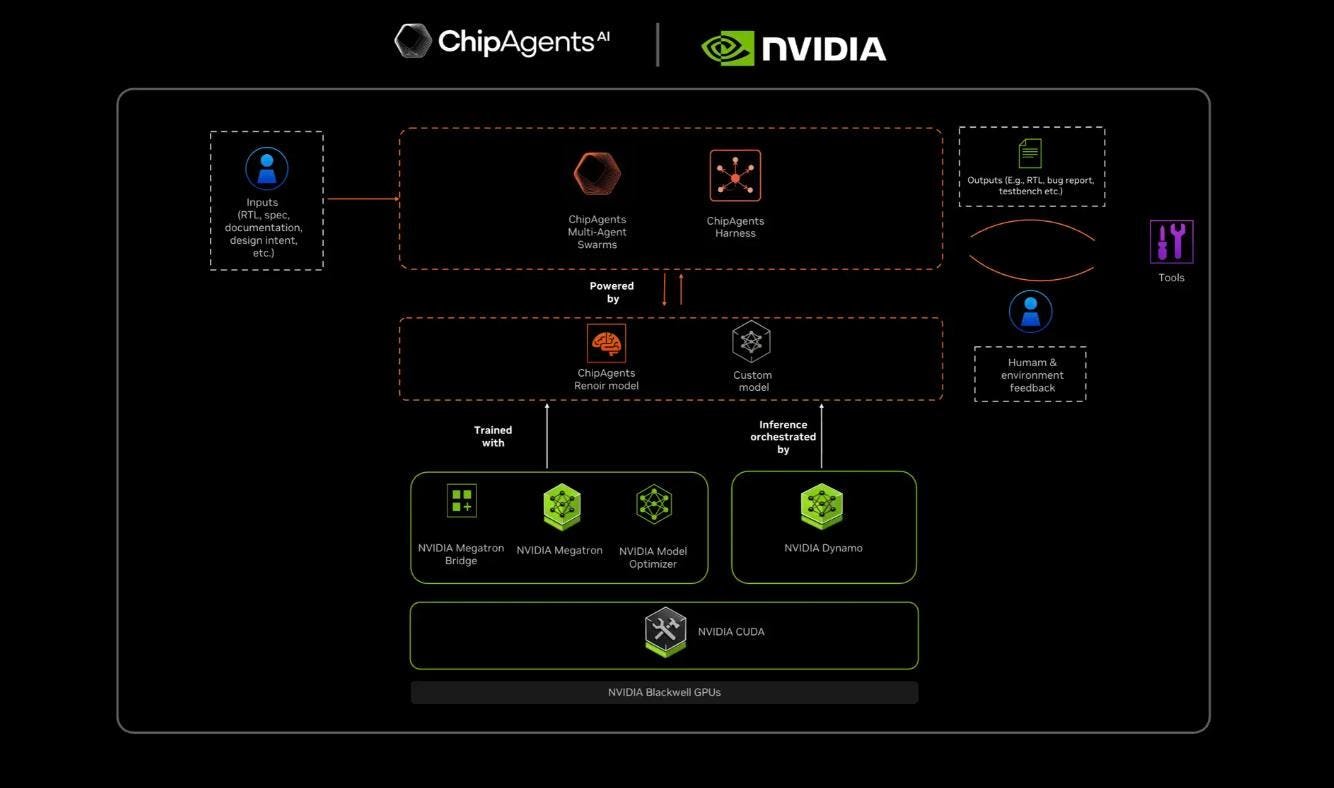
The semiconductor industry is currently undergoing a quiet yet seismic revolution. While the general public fixates on the latest consumer-facing generative AI models, a parallel race is unfolding deep within the foundational layer of modern technology: chip design. Just as foundational large language models like Anthropic's Claude have redefined natural language processing, a new wave of Electronic Design Automation (EDA) startups believes they can do the same for silicon engineering.
For decades, the EDA market has been heavily consolidated. Incumbents like Cadence Design Systems and Synopsys have dominated the landscape, providing the software tools that engineers use to lay out billions of transistors on tiny wafers of silicon. However, as chips become exponentially more complex—driven by the demands of artificial intelligence, high-performance computing, and advanced packaging—traditional EDA workflows are hitting a wall. Enter a new vanguard of AI-native EDA startups aiming to disrupt the status quo, introduce advanced machine learning loops into the design cycle, and potentially upend the industry's traditional pricing models.
The Bottleneck in Modern Silicon Engineering
Designing a modern system-on-a-chip (SoC) is one of the most intellectually and computationally demanding tasks in human history. Engineers must optimize for power, performance, and area (PPA)—a triad of competing constraints where improving one often degrades another. Traditionally, this process relies heavily on human heuristics, trial and error, and brute-force computing.
As node sizes shrink down to 3 nanometers and below, the physical effects of quantum mechanics, thermal dissipation, and signal integrity make the design space virtually infinite. While EDA giants like Cadence and Synopsys have begun integrating AI features into their massive legacy suites, these tools are often evolutionary rather than revolutionary. They serve to accelerate existing workflows rather than completely reimagine how chips are architected from the ground up.
Challenging the Incumbent Monopoly
This gap in the market has created an opening for agile startups. Unlike legacy providers bogged down by decades-old codebase architecture, new market entrants are building their software stacks natively around machine learning and reinforcement learning. These startups are betting that an "AI-first" approach can dramatically shorten design cycles, which currently take years and cost tens or even hundreds of millions of dollars per tape-out.
Industry watchers are closely monitoring how these startups plan to gain traction. Gaining adoption in the semiconductor space is notoriously difficult; chipmakers are risk-averse, and a single bug in an EDA tool can result in millions of dollars of ruined silicon. Therefore, these startups are not just selling better software—they are trying to prove that machine learning can find optimal floorplans and routing solutions that human engineers would never discover.
A Paradigm Shift in EDA Pricing Models
Perhaps the most fascinating implication of this startup wave is not just the technology itself, but what it portends for the business model of chip design. Historically, EDA software has been sold via hefty annual seat licenses and maintenance fees, regardless of how much value the tool generated or how many chips were ultimately produced.
If AI startups succeed in dramatically compressing the time-to-market and yielding superior PPA metrics, it could unlock entirely new monetization strategies. Much like how cloud computing and API-based AI models shifted software costs to usage-based models, successful EDA AI disruptors could pivot toward value-based pricing, outcome-based contracts, or a per-tape-out royalty structure.
| Feature / Dimension | Traditional EDA (Cadence / Synopsys) | Next-Gen EDA AI Startups |
|---|---|---|
| Architecture | Legacy codebases with bolted-on AI features | Native machine learning and reinforcement learning |
| Design Focus | Incremental optimization of human-driven layouts | Autonomous exploration of complex design spaces |
| Pricing Structure | Traditional seat licenses and annual maintenance | Emerging value-based, usage, or outcome models |
| Risk Tolerance | Proven reliability, deeply embedded in enterprise pipelines | High performance upside, working to build enterprise trust |
The Road Ahead for Silicon Intelligence
The race to become the "Claude of chip design" is more than just a battle of algorithms; it is a structural test of how foundational enterprise software will evolve in the age of artificial intelligence. While incumbents possess massive distribution networks, deep pockets, and decades of customer trust, nimble startups possess the architectural freedom to experiment wildly.
Whether these three prominent startups successfully capture market share or eventually become acquisition targets for the very giants they are trying to disrupt, one thing is certain: the methodology of building the world's microprocessors will never be the same. As AI begins to design the very hardware that runs AI, the semiconductor industry is stepping into a fascinating, highly accelerated loop of self-improvement.


