Navigating Monsoon-Related Automotive Damage: A Comprehensive Guide
The monsoon season brings much-needed relief from the scorching summer heat, but for vehicle owners, it often heralds a period of significant stress. Heavy rainfall, waterlogged streets, and unpredictable flooding can turn a reliable daily driver into a costly liability in a matter of minutes. According to recent reports from NDTV, understanding the nuances of your insurance policy during these periods is not just a matter of financial prudence—it is a necessity for ensuring your claim is successful.
When your vehicle sustains damage due to extreme weather, the difference between a successful insurance payout and a rejected claim often comes down to the actions you take in the immediate aftermath. As noted in the source material, the most critical step is to avoid the temptation to restart a stalled engine. Attempting to force a flooded engine to turn over can lead to hydrostatic lock, which causes catastrophic internal damage that insurers often classify as "consequential damage" rather than an accidental event, potentially leading to claim denial.
The Critical First Steps After Damage Occurs
The moment you realize your vehicle has been compromised by floodwaters, your priority should be documentation. Insurance adjusters require clear, timestamped evidence to process claims efficiently. You should immediately capture high-resolution photographs and record detailed videos of the water levels, the state of the vehicle, and the surrounding environment. This visual record serves as your primary defense during the claims assessment process.
Once you have secured documentation, your next step is to notify your insurer immediately. Most insurance companies have a 24/7 dedicated helpline for emergency claims. By reporting the incident promptly, you establish a timeline that aligns with weather reports in your area. Delaying this notification can lead to suspicion from the claims department and may complicate the verification process of how the damage occurred.
Understanding Coverage: When Insurance Pays
General motor insurance policies typically provide coverage for "natural calamities," which includes flooding, storms, and landslides. However, a standard Third-Party Liability policy will rarely cover the damage to your own vehicle. To be fully protected, you must hold a Comprehensive Policy or a standalone Own Damage (OD) cover. These policies are designed to handle the repair costs associated with electrical failures, interior water damage, and mechanical issues caused by rising water.
It is important to note that many modern cars are equipped with complex Electronic Control Units (ECUs). Water ingress can fry these systems, leading to astronomical repair bills. If you have opted for a "Zero Depreciation" add-on, your insurer will cover the entire cost of the replaced parts without deducting for the age of the vehicle. This is particularly valuable during the monsoon, as plastic and rubber components often require full replacement rather than repair.
When Insurance Might Not Pay
Not all monsoon-related damage is automatically covered. The most common reason for a rejected claim is the aforementioned "hydrostatic lock" caused by user negligence. If an owner is aware that an area is severely waterlogged but chooses to drive through it anyway, the insurer may view this as willful negligence. Furthermore, if the engine is restarted after the vehicle has stalled in water, the damage caused by that specific action is often excluded from the standard coverage.
Historically, insurance companies have seen a massive spike in claims during the months of July and August, coinciding with peak monsoon activity in various regions. Data from past years shows that urban centers with poor drainage infrastructure consistently report the highest volume of total-loss vehicle claims. Because of these trends, insurers have become increasingly stringent in their verification processes, making it essential for owners to be transparent and proactive about their claims.
Protecting Your Asset Beyond the Policy
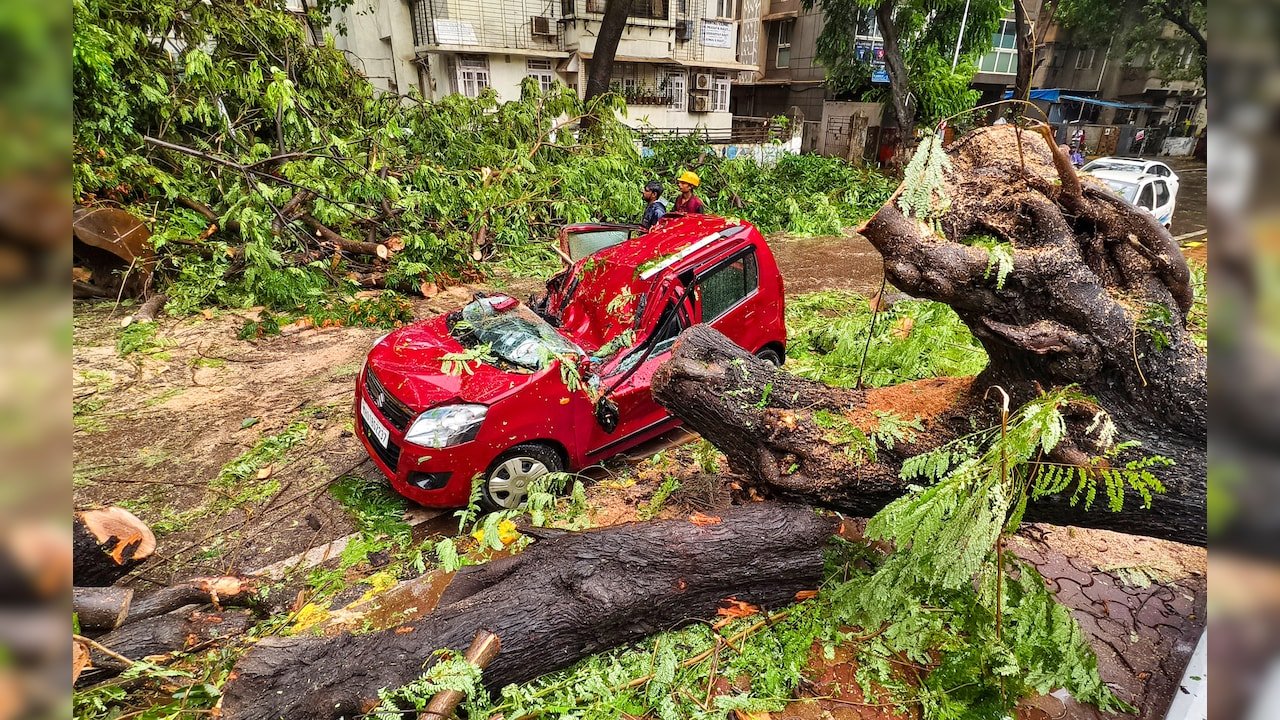
While insurance is your safety net, prevention remains the best strategy. During the monsoon, it is advisable to avoid parking your vehicle in low-lying areas or near large trees that could collapse under heavy wind. If you live in a flood-prone zone, consider investing in a Return to Invoice (RTI) add-on, which ensures that in the event of a total loss, you receive the full original purchase price of the car rather than its depreciated value.
Ultimately, the monsoon season is an unpredictable time for motorists. By following the guidance provided by industry experts and staying informed about the specifics of your coverage, you can mitigate the financial impact of environmental hazards. Remember, in the event of a disaster, your best tools are quick documentation, immediate communication with your insurer, and restraint when it comes to attempting DIY repairs on a water-damaged engine.


