Source: Australian Financial Review
Introduction
Global financial stability concerns have intensified as Morgan Stanley highlights growing distress within the private credit sector driven by an ongoing property market downturn. Financial institutions are increasingly scrutinizing private lenders as asset valuations shift and commercial real estate pressures mount. These market dynamics are drawing intense focus from major institutional investors and central banking authorities alike.
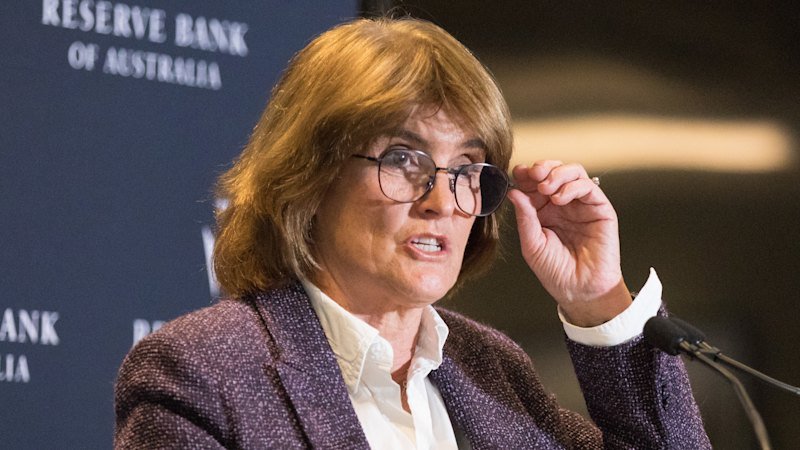
Compounding these financial sector anxieties, Reserve Bank of Australia Governor Michele Bullock has voiced distinct apprehensions regarding the shadow banking ecosystem. Specifically, the central bank leader pointed to a profound lack of operational visibility among non-bank lenders operating overseas. As regulatory scrutiny heightens, market participants are grappling with the systemic risks posed by these opaque financing channels.
What Happened
The intersection of property market corrections and private lending vulnerabilities has created a distinct financial headache for major financial institutions. According to assessments from Morgan Stanley, the property downturn is exposing structural vulnerabilities within private credit portfolios. This environment has generated widespread unease across global capital markets regarding asset quality and liquidity.
Simultaneously, regulatory figures have stepped up public warnings regarding the hidden mechanics of non-bank financial intermediation. Reserve Bank of Australia Governor Michele Bullock emphasized that her primary worry centers on the United States market. Within the US non-bank lending sphere, a severe deficit of transparency hinders proper risk assessment by regulators and investors.
Background
Private credit has expanded rapidly in recent years, stepping in as traditional commercial banks tightened lending standards for real estate and corporate borrowers. This alternative financing sector operates largely outside the stringent regulatory perimeters governing traditional banking institutions. Consequently, non-bank lenders have accumulated substantial market share in funding commercial property and corporate ventures.
However, this rapid growth has occurred with limited public reporting standards compared to publicly traded banks. Financial authorities have increasingly monitored this segment for potential systemic contagion risks. The current property downturn serves as a critical stress test for these lightly regulated credit vehicles.
Key Details
| Focus Area | Key Entity / Individual | Primary Observation |
|---|---|---|
| Private Credit Vulnerability | Morgan Stanley | Property downturn is generating private credit challenges. |
| Regulatory Concern | Michele Bullock (RBA Governor) | Expressing worry regarding non-bank transparency. |
| Geographic Focus | United States | Opaque non-bank lending environment identified as a key risk area. |
The nexus between real estate valuation adjustments and private debt obligations remains a core vulnerability. Industry analysts note that diminished visibility into non-bank balance sheets complicates efforts to gauge the true extent of credit stress. These structural challenges are reshaping risk management protocols across international financial institutions.
Impact
The warnings from both Morgan Stanley and Reserve Bank of Australia Governor Michele Bullock underscore broader anxieties about financial system transparency. As property values face downward pressure, private credit funds exposed to real estate may experience valuation write-downs. Investors allocating capital to alternative lending strategies are being forced to reassess their risk exposure.
Furthermore, the lack of disclosure among US non-bank lenders creates uncertainty that can spill over into broader financial markets. Regulators are increasingly concerned that hidden leverage within the shadow banking system could amplify market shocks. This dynamic places institutional lenders and asset managers under heightened scrutiny from international watchdogs.
What Happens Next
Market observers anticipate continued close monitoring of non-bank financial institutions by central banks and global financial authorities. As the property downturn continues to evolve, market participants will look for further disclosures regarding private credit asset quality. Regulatory bodies are expected to maintain pressure on improving transparency standards across the alternative lending landscape.

