Source: Australian Financial Review
Introduction
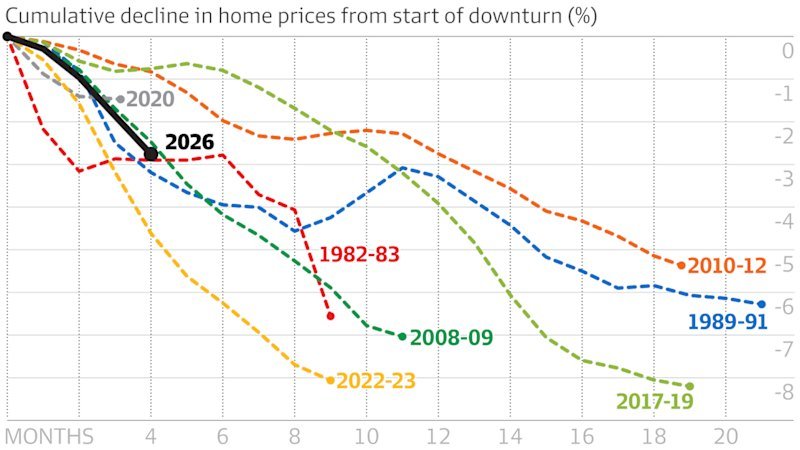
Property downturns rarely last, but experts warn that the current contraction in the housing sector could be entirely different. Market analysts suggest that ongoing economic pressures might turn this real estate correction into the worst decline seen in decades.
Prospective buyers and current homeowners face a uniquely challenging environment as property values encounter severe headwinds. With affordability already stretched to historic extremes, the combination of macroeconomic shifts and policy alterations threatens to prolong the current market slump.
Industry specialists are closely monitoring the situation as traditional recovery patterns fail to materialize. The convergence of multiple negative catalysts indicates that standard historical models for real estate rebounds may no longer apply to the present economic landscape.
What Happened
The Australian residential property market has entered a severe correction phase characterized by deep structural challenges. Analysts emphasize that the current trajectory diverges sharply from previous cyclical downturns that typically saw swift recoveries.
Housing accessibility has deteriorated to critical levels, locking out numerous potential participants from entering the property market. This widespread unaffordability creates a bottleneck that stifles natural market turnover and suppresses overall transaction volumes across the board.
Simultaneously, the broader financial climate has deteriorated, removing the customary supports that usually cushion the sector during corrections. Consequently, experts point to these compounding factors as the primary drivers behind the unprecedented severity of the ongoing downturn.
Background
Historical precedents show that real estate contractions are typically short-lived episodes followed by robust market revivals. Low borrowing costs and government incentives have traditionally stimulated demand and restored upward momentum to property values following brief cooling periods.
However, the current market cycle lacks these historical shock absorbers. Housing accessibility had already reached severe constraints prior to the onset of the downturn, leaving little buffer for buyers or investors navigating the changing economic terrain.
Furthermore, policy frameworks governing the real estate sector are undergoing significant shifts. These regulatory and fiscal adjustments alter the calculus for market participants who relied on previous tax structures to sustain their property holdings.
Key Details
A comprehensive examination of the factors driving the current real estate correction highlights several distinct elements. Analysts have outlined the primary components contributing to the prolonged downturn.
| Market Factor | Current Status |
|---|---|
| Interest Rates | Rate cuts remain a distant prospect |
| Housing Affordability | Already severely restricted |
| Tax Policy | Significant changes to investor tax breaks |
| Market Severity | Potentially the worst downturn in decades |
These core elements illustrate the complex web of pressures confronting the residential property sector. Each variable interacts to restrict market liquidity and dampen investor confidence.
Impact
The unfolding contraction carries profound implications for property investors, developers, and everyday households. Alterations to investor tax breaks fundamentally reshape the financial feasibility of holding residential real estate assets.
With monetary policy expected to remain restrictive, the absence of near-term rate reductions removes a vital catalyst for market revitalization. Borrowing power remains constrained, limiting the pool of qualified purchasers capable of transacting at current valuation levels.
The combination of these pressures threatens to depress market activity for an extended duration. Observers note that prolonged stagnation could reshape wealth distribution and housing tenure patterns throughout the affected markets.
What Happens Next
As the sector navigates these uncharted waters, market participants must adapt to a prolonged period of adjustment. The persistence of high borrowing costs and altered tax regulations means that standard cyclical relief is unlikely to arrive soon.
Experts will continue to monitor policy announcements and broader macroeconomic indicators for any signs of a structural shift. Until tangible relief emerges on the monetary or fiscal front, the property sector faces an extended and severe test of its resilience.

