Source: Live Mint
Introduction
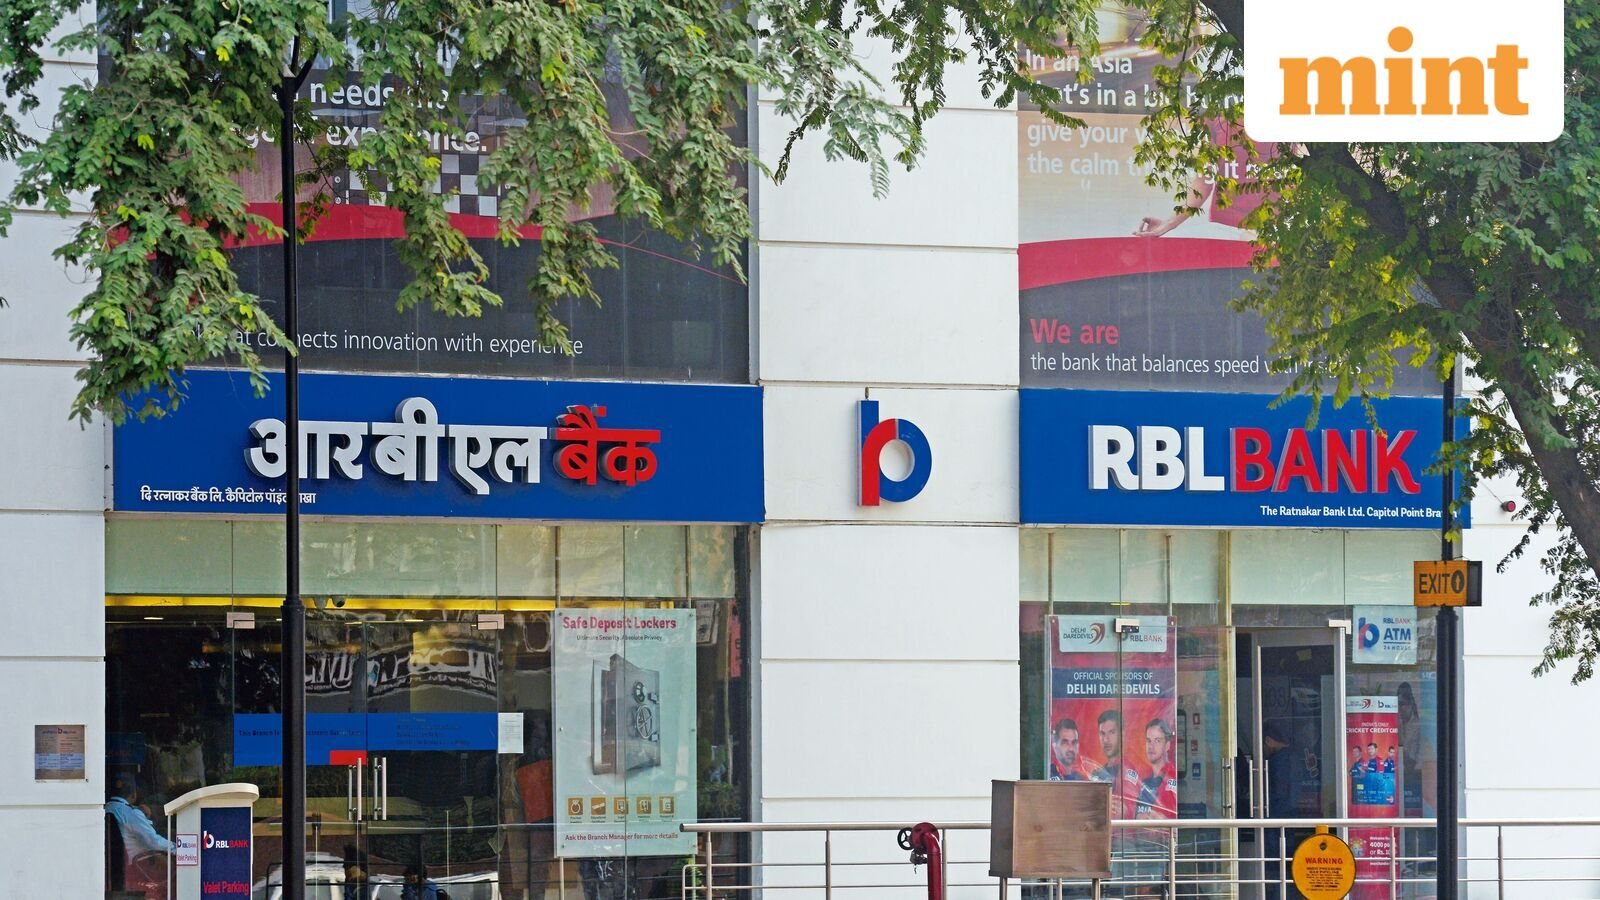
The recent volatility in RBL Bank’s market performance has drawn significant attention from financial analysts and shareholders alike. Central to this investor interest is the bank's strategy regarding Foreign Currency Non-Resident (Bank) or FCNR (B) deposits, which have become a focal point of market discussions.
As stakeholders evaluate whether the current investor frenzy over FCNR (B) deposits is justified, it is essential to look past the immediate market reaction. While these inflows have provided a tangible boost to the lender's liquidity profile, the long-term sustainability of this strategy remains a subject of rigorous debate among industry observers.
What Happened
RBL Bank has experienced a noticeable uptick in its stock price, a development largely attributed to market optimism surrounding its recent success in attracting FCNR (B) deposits. Investors appear to be reacting positively to the bank’s ability to secure these foreign currency funds, viewing them as a catalyst for growth.
The influx of these deposits has effectively expanded the bank's total deposit pool. This expansion is perceived by the market as a significant lever for increasing the lender's overall capacity to extend credit, thereby signaling potential revenue growth in the upcoming quarters.
Background
FCNR (B) accounts are specialized deposit products that allow non-resident Indians to maintain funds in foreign currencies. For a financial institution like RBL Bank, these deposits represent a specific form of liability management that can be utilized to bolster the balance sheet.
Historically, banks use these instruments to manage foreign exchange assets and enhance liquidity. However, reliance on such inflows is distinct from traditional retail banking strategies that prioritize stable, domestic deposit mobilization.
Key Details
To better understand the current financial narrative surrounding RBL Bank, it is helpful to categorize the key operational factors driving the market sentiment.
| Factor | Operational Significance |
|---|---|
| FCNR (B) Inflows | Primary driver of recent market excitement and stock price movement. |
| Deposit Expansion | The immediate result of foreign currency inflows, increasing the bank's liquidity. |
| Lending Capacity | The anticipated functional benefit resulting from the expanded deposit base. |
| Market Sentiment | Reflects high investor expectations regarding the bank's growth trajectory. |
Impact
The immediate impact of the FCNR (B) strategy is a strengthened liquidity position for RBL Bank. By increasing the volume of available funds, the bank is theoretically better positioned to meet credit demand and capitalize on lending opportunities that might have otherwise been constrained.
However, the broader market impact is nuanced. While the stock surge demonstrates investor confidence, there is a lingering concern regarding the quality and stability of this funding source. Unlike core domestic deposits, which are often sticky and provide a foundation for long-term retail banking, foreign currency deposits can be sensitive to global interest rate fluctuations and exchange rate volatility.
What Happens Next
Looking ahead, the primary challenge for RBL Bank will be the conversion of these liquidity gains into sustainable, long-term profitability. Market analysts are closely monitoring whether this windfall will act as a temporary measure or if it can be integrated into a more comprehensive growth strategy.
A critical question facing the bank is whether these foreign currency inflows can successfully substitute for the arduous task of building a deep and resilient domestic deposit base. The realization of the benefits associated with this strategy is expected to be a gradual process, and investors will likely remain focused on how the bank balances its reliance on external funding with its traditional domestic banking operations.
As the bank moves forward, the market will likely scrutinize whether the current momentum can be maintained without compromising the stability of the bank's funding profile. The transition from speculative excitement to demonstrated performance will be the defining factor in determining the long-term justification for the current investor interest.