Understanding the Tax Implications of International Sports Prizes in the United States
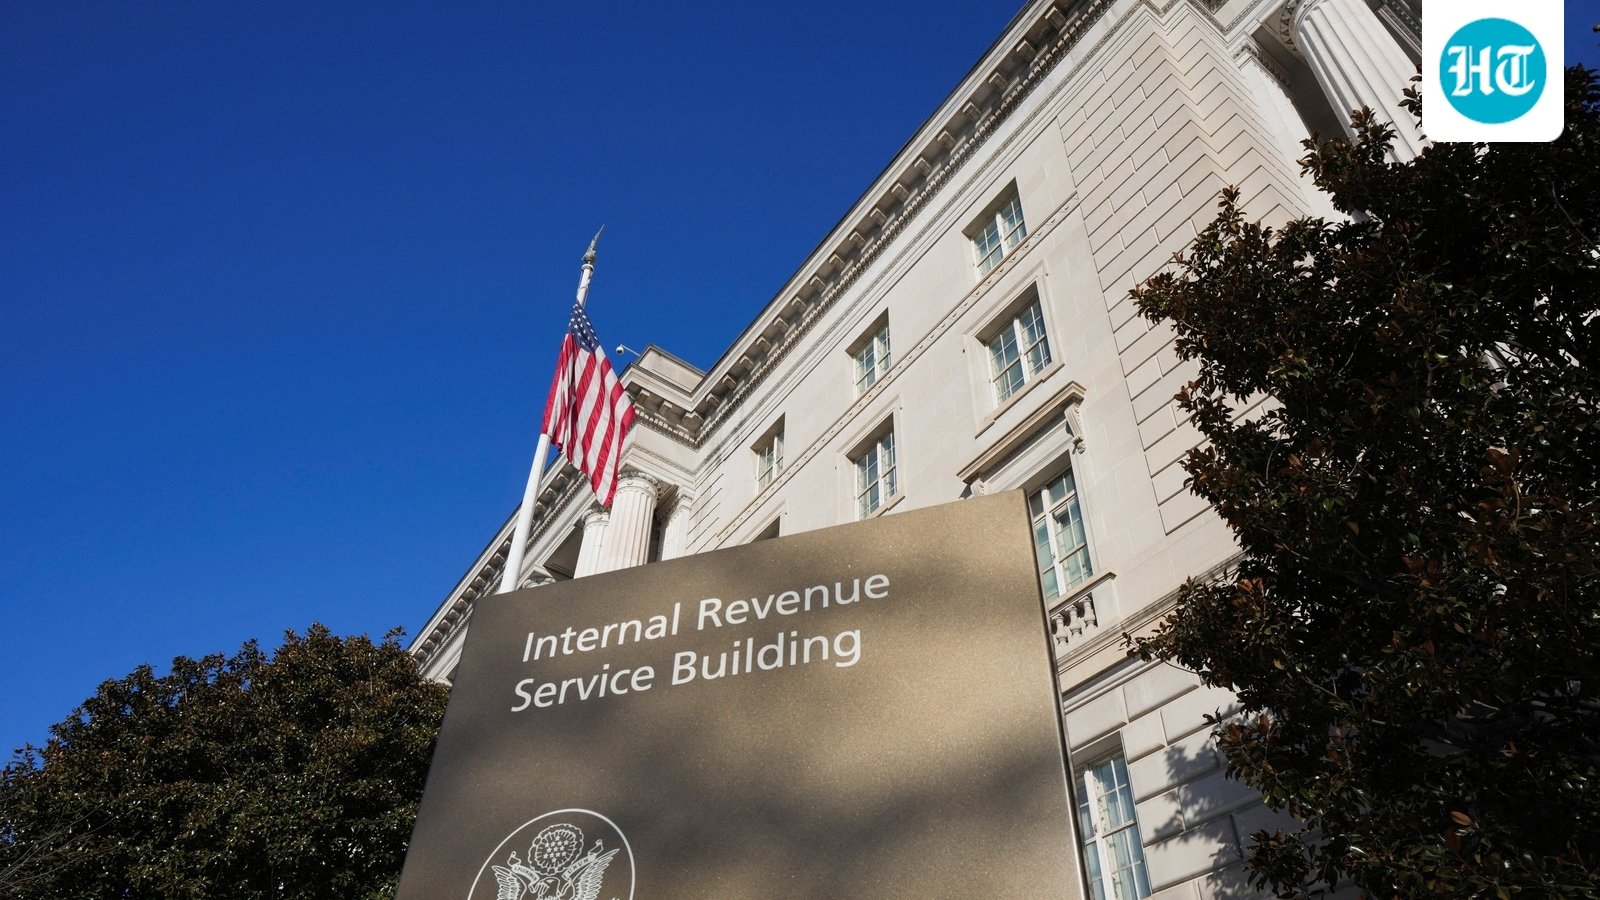
When national athletic teams achieve the pinnacle of success on the global stage, the celebrations are usually accompanied by massive financial windfalls. However, international tax laws, jurisdictional boundaries, and domestic tax codes can significantly diminish those earnings long before the champions ever return home. A striking example of this complex intersection between international sports and domestic taxation involves Spain’s monumental $50 million FIFA World Cup prize money. Because portions or the entirety of the tournament events are hosted within the sovereign borders of the United States, the Internal Revenue Service (IRS) and various state tax authorities view these earnings through a very specific legal lens.
Navigating the labyrinth of American tax policy can be daunting for domestic citizens, but for international athletes, it presents an unprecedented web of multi-jurisdictional obligations. The concept that foreign entities can be subjected to U.S. federal taxation stems from the principle of source-based taxation. When income is generated within the geographical boundaries of the United States, the federal government asserts its right to levy taxes on those earnings, regardless of the recipient's residency status. This reality catches many international sports associations and athletes completely off guard when they calculate their net take-home pay after a major tournament.
The Mechanics of IRS Taxation on World Cup Earnings
The primary driver behind the potential taxation of Spain's massive prize fund is the physical location of the tournament's hosting duties. Under U.S. federal tax law, non-resident alien athletes and foreign corporations earning income effectively connected with a trade or business within the United States—or earning certain types of U.S.-source fixed, determinable, annual, or periodical income—are subject to federal income tax withholding. Consequently, the IRS will take a substantial cut of Spain's $50 million FIFA World Cup prize money simply because the economic activity and events occurred on American soil.
To fully grasp how these financial deductions impact both the governing athletic body and the individual players, it is essential to examine the breakdown of potential tax liabilities. While the federation faces federal corporate withholding rates, the individual athletes must also contend with progressive income tax brackets and specialized state levies. The financial burden is not distributed evenly, as different states apply varying tax methodologies to earnings generated within their specific jurisdictions during high-profile sporting events.
| Tax Category | Affected Entity | Estimated Impact / Details |
|---|---|---|
| Federal Income Tax | Spanish Football Federation / Players | Subject to standard U.S. federal tax withholding rates on U.S.-sourced income. |
| State Jock Taxes | Individual Players | Levied by specific U.S. states where matches or training sessions are physically hosted. |
| Total Prize Fund | Spain's FIFA World Cup Earnings | Valued at $50 million, subject to multi-layered tax reductions. |
The Complex Reality of State "Jock Taxes" for Elite Athletes
Beyond the federal requirements enforced by the IRS, individual players representing Spain will also face the notoriously complex arena of state "jock taxes." A jock tax is an income tax levied against athletes and entertainers who earn money while working within a specific state or municipality other than their official home residence. Because a tournament like the FIFA World Cup often spans multiple host cities across different American states, players are legally obligated to file tax returns and pay taxes in every single state where they stepped onto the pitch or engaged in revenue-generating athletic work.
This fragmented approach means that a single tournament can require a player’s financial team to calculate earnings down to the exact day—or even the exact hour—spent in a particular stadium or training facility. States calculate these liabilities by taking the athlete's total compensation for the event and multiplying it by a "duty days" fraction. This fraction represents the number of days spent working in that specific state divided by the total number of working days in the entire taxable period. For international stars who are accustomed to simpler tax structures in Europe, navigating the American jock tax system is an exceptionally frustrating and costly endeavor.
Conclusion: The True Cost of Competing on American Soil
Ultimately, the intersection of international sports economics and American tax law serves as a stark reminder that global earnings are rarely kept intact. While securing a $50 million prize pool is an extraordinary athletic and commercial achievement for the Spanish squad, the administrative and financial reality of U.S. taxation cannot be ignored. Between the sweeping reach of the IRS and the intricate web of state-level jock taxes, a significant portion of these hard-earned funds will remain in the United States. As global sporting events increasingly look to the U.S. as a premier destination for hosting, international sports federations must proactively factor these rigorous tax implications into their financial planning.